

Financial missteps sink more startups than product failures, yet many entrepreneurs still launch without mastering the metrics that separate sustainable businesses from expensive experiments. This guide compiles 25 essential concepts drawn from seasoned CFOs, venture advisors, and operators who have scaled companies through multiple funding cycles. Each principle addresses a specific blind spot that drains resources, delays profitability, or limits strategic options when growth accelerates.
- Prioritize Runway Over Paper Gains
- Master COGS Before You Charge
- Compute Real Per-Product Profit
- Fix Unit Economics Before You Scale
- Audit Per-Customer Surplus By Channel
- Optimize Gross Margin Per Account
- Distinguish Cash From Accrual Realities
- Command Your Capital Turnover Cycle
- Use Leverage To Multiply Outcomes
- Measure Net Gain Per Delivery Unit
- Count Cleared Funds Ignore Verbal Promises
- Secure Cushion With Early Pipeline
- Reduce DSO With Human Collections
- Know And Explain Your Financials
- Favor Fast Payback Over Vanity Growth
- Maintain Disciplined Liquidity Reviews
- Reinvest Early Gains For Speed
- Price Work To Reflect Risk
- Protect Optionality With Lean Spend
- Track Earned Value Against Plan
- Turn Capex Into Shared Infrastructure
- Differentiate Valuation From Buyer Attractiveness
- Separate Business And Personal Accounts
- Adopt AI Where It Pays Back
- Assess Total Cost Of Ownership
Prioritize Runway Over Paper Gains
For me, every entrepreneur must understand the importance of cash flow. Valuations are speculative. Revenue measures scale. Profit measures efficiency. Cash flow determines survival. The only place you can have a negative cash flow is in Excel. Not in real life.
Early in my entrepreneurial journey, one of our B2B businesses was growing rapidly. Larger clients were signing purchase orders, invoices were being raised, and on paper everything looked excellent. We were approaching a million dollars in sales. The problem was that many clients paid 60 to 90 days later, while salaries, rent, and vendor payments had to be made every month.
We reached a point where the business was profitable on paper, yet the cash in the bank had almost disappeared. To keep the company alive, I had to inject personal funds for 4 months and endure significant financial hardship while waiting for payments I had already earned.
That experience taught me a lesson I have never forgotten. A growing company can fail because of poor cash flow management, even when sales are increasing.
We responded by tightening payment terms, collecting advances wherever possible, improving receivables tracking, and maintaining a cash reserve. The result was greater stability and far less financial stress during future growth phases.
Even today, when I mentor startups, valuation is rarely my first question. Revenue is usually my second. My first question is always, “How many months of runway do you have, and what does your cash flow look like?”
Understanding cash flow helped us build multiple profitable ventures over the years by prioritizing free cash flow.
Master COGS Before You Charge
The single most important financial concept every entrepreneur needs to master is cost of goods sold, or COGS, and more specifically, knowing your true margin on every single product you sell. It sounds basic, but it’s where most small businesses quietly bleed money without realizing it.
When we launched Equipoise Coffee in 2021, I was so focused on the craft side, sourcing high-quality beans and dialing in roasting science to eliminate bitterness, that I almost treated the numbers as an afterthought. That’s a trap. Specialty coffee has real costs baked into it: green bean prices fluctuate, roasting has yield loss, and small-batch production means you don’t get the volume discounts the big guys do. If you price off gut feeling, you’ll convince yourself you’re profitable when you’re actually subsidizing every bag.
The moment it clicked for me was when we mapped out the full cost on one of our single-origin offerings. I tracked everything: the green coffee, the weight lost during roasting, packaging, labels, and the labor of small-batch roasting. The “obvious” retail price I’d had in my head left almost no room once all of that was accounted for. Understanding the real margin let me price with confidence instead of guilt, and it actually freed me to explain to customers why premium, freshly roasted coffee costs what it does. That transparency builds trust rather than scaring people off.
Here’s my advice: build a simple spreadsheet for every product and account for the costs people forget, especially weight loss in production and the time your own hands put in. Know your margin before you set a price, not after. When resources are tight, that clarity tells you exactly where to focus and what’s actually worth making. Balance isn’t just our coffee philosophy, it’s how a small business stays standing.

Compute Real Per-Product Profit
The concept that changed everything for me was contribution margin, not just overall revenue or profit, but understanding exactly how much each product line contributes after variable costs.
When I started Simply Noted in 2018, I was focused on top line revenue like most first time founders. Sales were growing but I could not figure out why cash was always tight. Once I broke down contribution margin by product, I realized our lowest priced note packages were actually losing money after you factored in postage, card stock, ink, and labor. We were literally paying customers to buy from us on certain SKUs.
That one analysis led me to restructure our entire pricing model. I killed the packages that were underwater, raised prices on our most popular options by about 15 percent, and introduced tiered bulk pricing that rewarded higher volume orders. Revenue dipped slightly for two months, but profitability jumped almost immediately. Within a quarter, our margins improved by over 20 percent and we finally had cash to reinvest in new robotics development.
Every entrepreneur should sit down and calculate the true contribution margin of every product or service they sell. Not the back of napkin version, the real one with every variable cost included. You will almost certainly find at least one thing that is costing you money while looking profitable on the surface.
Fix Unit Economics Before You Scale
The concept I would put at the top is unit economics, specifically understanding what it actually costs to serve one customer and what you actually make from them, before you scale anything. Most founders think they understand this and then quietly skip the work, because the real numbers are uncomfortable and the spreadsheet that solves for them is annoying to build. The thing nobody tells you is that scale does not fix bad unit economics, it amplifies them. If you lose a little money on every customer, growth is the worst thing that can happen to you, and I have watched smart founders run straight into that wall because they were measuring revenue instead of contribution margin.
The specific moment it mattered for us was when we designed our clinician compensation structure. We run a network of independent licensed clinicians, and the obvious move would have been to set one rate and call it done. Instead I forced us to model the actual economics per session type and per clinician credential, because a senior psychologist working a long appointment carries a completely different cost structure than a master’s-level clinician working a standard one. We ended up building a tiered structure that paid clinicians what their work was actually worth while leaving a margin that could fund the operations a network actually needs: intake, billing, technology, marketing, all the things that vanish if the unit math is wrong. The lesson I would give other founders is to do that math before you raise, before you grow, and before you set a single price, because every other decision in the business ultimately gets adjudicated by it.
Audit Per-Customer Surplus By Channel
Contribution Margin Per Customer Beats MRR
Most founders track MRR and EBITDA. Both miss the question that actually decides whether your business compounds: which specific customer, acquired through which specific channel, is profitable to serve? The answer lives in contribution margin per customer, segmented by acquisition channel and pricing tier. Contribution margin is revenue minus direct variable cost to serve that customer, before any allocated overhead. MRR is a top-line number. EBITDA is a company-level number. Neither tells you whether the next dollar you spend acquiring a customer through a given channel will come back to you with a margin attached.
At VoiceAIWrapper, I learned this the expensive way. We run a white-label voice AI platform for agencies, and for a stretch our paid Google Ads channel looked healthy on the surface. Top-line revenue from that channel was strong, signup volume was high, and the spreadsheet said grow it. When I finally cut the data to contribution margin per customer by acquisition channel, the picture inverted. The Google Ads cohort had roughly 4x higher support cost than our SEO cohort because they arrived with no context about the product. They asked basic questions, needed hand-holding through setup, and churned at about 2x the rate of customers who came in through our comparison content. On a 24-month basis, contribution margin on that cohort was negative. We were paying to acquire customers who cost us money to keep.
The decision was uncomfortable but mechanical. I cut Google Ads spend by around 80% and redirected the budget into comparison page SEO, where prospects arrived already educated about the category, already self-qualified against alternatives, and converted with lower support overhead per customer. Within six months, total trial signups dropped slightly. Contribution margin per active customer roughly doubled. The business felt smaller on the surface and was healthier underneath.
The rule I now apply to every revenue decision: every revenue line item needs a paired contribution margin line item. If you cannot calculate the variable cost to serve that specific cohort, you do not know whether you are growing profitably or growing the wrong customers faster.
Optimize Gross Margin Per Account
Gross margin per client, not total revenue, is the number that actually runs a service business. I learned this the hard way. We had a month where we hit our highest gross revenue ever running a done-for-you service operation. I thought we’d turned a corner. When I broke down gross margin per account, two clients that looked like strong revenue were costing us more in fulfillment hours than they generated in profit. We were literally growing ourselves into a loss.
Once I understood that gross margin per client was the unit to optimize, everything changed. Pricing decisions got sharper. I stopped taking on accounts where the fulfillment model required too many hours to deliver the result. I started looking at what each account was actually worth after cost of delivery, not the invoice amount.
The practical version of this for any service founder: take your monthly revenue from a client, subtract every direct cost to fulfill that client including labor hours, tools, and software, and see what’s left. Do that for every account. You’ll often find your fastest-growing clients are your worst gross-margin clients because you’ve been underpricing the complexity.
Revenue is vanity. Gross margin per account tells you whether the business is actually working. Know it before you scale.
Distinguish Cash From Accrual Realities
Dane Maxwell, founder of Paperless Pipeline, a SaaS bootstrapped on cash flow since 2009. The financial concept I would say every entrepreneur should understand has shaped every meaningful operating decision I have made across 17 years. Happy to share.
The concept: The distinction between cash and accrual accounting, and specifically the lag between when revenue is recognised on paper and when the cash actually arrives in the bank account.
What this means in practice: The income statement might show a profitable month while the cash position is shrinking. Or the income statement might show a loss while the bank balance is rising. Both are common in service businesses, subscription businesses, and any business where customers pay on terms or where deferred revenue accumulates. The entrepreneur who reads only the income statement gets a misleading picture of business health.
The specific instance where this saved our business: In year 4 of our company, we landed a meaningful new customer who signed an annual contract and paid the full year upfront. The accrual income statement recognised the revenue monthly across the 12-month service period. The cash hit our account in full on day one. Without understanding the distinction, I might have treated the bank balance as available operating capital and spent it on growth investments. Understanding it meant I segregated the prepaid revenue, treated only the earned portion as available, and avoided a cash crunch that would have hit when the customer’s renewal was due 12 months later.
The practical practice that flows from understanding this: We track three numbers weekly. Operating cash balance (current bank balance minus near-term obligations). Earned-but-uncollected revenue (work performed that has not yet been paid). Collected-but-unearned revenue (cash received in advance for service that has not yet been delivered). The three numbers together tell us what we actually have, what we are owed, and what we owe in service.
The recommendation: Every entrepreneur should be able to explain their cash position separately from their income statement, every week. Confusing the two is the single most common failure mode I see in founders who never learned the concept.
Command Your Capital Turnover Cycle
Back in 2020, I almost made a huge mistake buying a distressed home goods company. The balance sheet looked okay, not great, but workable. Then I did something that saved me: I mapped out the actual cash conversion cycle against what we owed suppliers. Turns out we’d be sitting on inventory for four months before seeing any liquid cash. That changed everything about how I negotiated the deal and structured the financing.
Here’s the thing: it doesn’t matter if you’re profitable on paper if you can’t cover next week’s payroll. I’ve seen it happen more times than I can count, entrepreneurs running businesses that look good in a spreadsheet but fail because they think revenue is the same as having cash on hand. Track your cash conversion cycle like your life depends on it. Because the difference between growing your business and constantly firefighting often comes down to that one number.
Use Leverage To Multiply Outcomes
One financial concept that every entrepreneur should understand is leverage. Most people associate leverage with borrowing money, but it’s much broader than that. Leverage is about using resources beyond your own time, effort, and capital to achieve greater results. That could be money, people, systems, partnerships, or knowledge.
Understanding leverage completely changed the way I built my businesses. When I started investing in property, I didn’t have huge amounts of capital. Like many aspiring entrepreneurs, I initially thought I needed a lot of money before I could grow.
However, once I learned about creative finance and deal structuring, I realised that wealth isn’t always created by having more money; it’s often created by using resources more effectively. A specific example was when I began using creative property strategies such as lease options. Instead of needing large deposits to buy every property, I learned how to structure deals that benefited both parties while requiring significantly less capital upfront. That shift in thinking was a turning point. I stopped asking, “How can I afford this?” and started asking, “How can this be structured so it works for everyone involved?” That simple change opened doors that I previously thought were closed.
The same principle applied when growing my education company. In the early days, I tried to do everything myself. But eventually, I realised that if the business depended entirely on me, its growth would always be limited. Building teams, creating systems, and empowering others allowed the company to scale far beyond what I could have achieved alone.
Many entrepreneurs believe the answer is simply working harder. Hard work matters, but leverage is what allows your efforts to multiply. There are only so many hours in a day, so understanding how to create greater impact through people, systems, and smart financial decisions is essential.
Looking back, many of the biggest breakthroughs in my career came from understanding and applying leverage effectively. If there’s one financial concept I’d encourage every entrepreneur to master, it’s this: learn how to multiply resources rather than rely solely on your own. That’s often where real growth begins.
Measure Net Gain Per Delivery Unit
One financial concept every entrepreneur should understand is contribution margin by delivery unit. Revenue can look healthy while every added client quietly increases operational strain and lowers true profitability. In agency environments, the important question is not top line growth, it is whether each seat, workflow, and account layer creates surplus after labor, revisions, management time, and quality control are accounted for. I learned early that scale without margin discipline creates complexity faster than value.
That became clear during a period of rapid partner expansion. New accounts were arriving consistently, but fulfillment pressure was rising faster than expected. A contribution review showed certain engagement structures consumed far more oversight than their pricing justified. Rebuilding workflow scope, approval paths, and account allocation restored margin, improved delivery consistency, and protected retention.
Count Cleared Funds Ignore Verbal Promises
The most underrated financial concept for founders is the difference between a verbal commitment and actual capital. In 2022 I had $10 million verbally committed for the Continuity Fund. Then investors vanished. We rebuilt from scratch, spent all of 2023 pitching, and closed $7 million. That experience rewired how I think about cash and runway.
The financial concept every founder needs to internalize is runway, not revenue. Revenue feels good, runway is what keeps you alive. The specific moment this crystallized for me was in 2022, when I had $10 million verbally committed for a fund, watched it evaporate almost overnight, and had to rebuild from scratch. We spent all of 2023 pitching hundreds of times to reach a first close of $7 million. Verbal commitments are not money. Cash in the bank is the only number that matters, and every decision you make, every hire, every partnership, every “probably coming through soon” should be stress-tested against the hard version of that number, not the optimistic one.
“The ones who ghost you stay warm for months, ask for more materials, then go quiet – no closed door, no honest no, just silence while you plan around a maybe.”
Until the wire clears, keep pitching.
Secure Cushion With Early Pipeline
One key financial concept every entrepreneur must master is Runway Management paired with a Pipeline Buffer. In the early days of building our startup company, we learned this the hard way. We got so overwhelmed managing a high volume of clients simultaneously that our communication slipped, leading to delayed responses. Consequently, when those contracts ended, we found ourselves completely out of clients and struggling financially to cover basic operational needs. That crisis taught us that you must anticipate client churn at least three months in advance. By constantly tracking our runway and actively building a sales pipeline months before existing contracts expire, we secured a vital financial cushion. This proactive planning ensures a steady cash flow, allowing us to run a smooth business entirely free from survival tension.
Reduce DSO With Human Collections
One financial concept that fundamentally changed how we manage cash at distribute is Days Sales Outstanding–specifically, the operational cost of friction in actually collecting what you’re owed. We used to look at our booked revenue and assume we were doing fine, but we had a noticeable lag in our actual bank balance because of routine failed payments and expired credit cards. Initially, we relied on standard, polished CRM templates to chase those accounts. They were sterile ‘Action Required’ emails, and customers usually either ignored them entirely or felt awkwardly targeted by an aggressive automated system. That friction stretched our collection time out for weeks.
We decided to strip away all the professional fluff to see if we could speed up our cash conversion. We changed the trigger in our CRM to send a plain-text email on day three after a failure that looked like a quick, messy note from my own inbox. The message simply said: ‘Hey, looks like the card on file bounced for your last invoice. Usually happens when a card expires or a bank flags a new charge–mind taking a quick look when you have a second?’ Dropping the dressed-up corporate warning for a raw, casual message caused our immediate collection rates to spike, bringing that trapped cash into the business significantly faster.
Know And Explain Your Financials
Understand your financials and be able to explain them
I see loan applications all day. The business owners who maintain their profit and loss and balance sheet, and can easily provide them, get approved at much higher rates. Lenders want to see that you know what you make, what you owe, and where you want to go. If you have to ask your accountant for every single document, you’re not in as strong a position.
Sometimes our applicants get declined, but because they keep their books updated, they can explain something that underwriting missed. We’ve had four or five applicants in the last two years get declines reversed because they could tell the story of their books. A restaurant with a line item for a one-time equipment replacement was able to show it wouldn’t be a recurring expense, and turned a $40,000 decline into a $40,000 approval.
Being able to explain your numbers is an advantage at every stage of business.
Favor Fast Payback Over Vanity Growth
The one financial concept every entrepreneur should understand is cash flow, specifically the difference between revenue you have booked and cash you actually have available to run the business.
That sounds simple, but it changes how you make decisions. In a software business, it is easy to look at top-line growth, new signups, or projected recurring revenue and assume you can keep increasing spend. What matters just as much is when cash actually comes in and how that timing lines up with payroll, tools, contractors, and other operating costs.
One practical metric connected to this is customer acquisition payback. I look at how much it costs to acquire a customer and how quickly that cost comes back in usable cash. That creates a better decision rule than just asking whether a channel is generating activity.
A useful example is when multiple growth channels all appear to be working at the same time. Some may drive signups, but if the payback window is too long, they can still create pressure on runway. In that situation, understanding cash flow helps you separate efficient growth from growth that only looks good in a dashboard.
The adjustment is straightforward: cut or slow the channels that tie up cash too long, and put more budget into the channels that return cash faster and more predictably. That does not just improve efficiency. It also gives the business more control, more flexibility, and less pressure to chase vanity metrics.
My general rule is this: revenue tells you whether there is demand, but cash flow tells you whether the business is operating sustainably. Entrepreneurs who understand that distinction usually make calmer, better decisions.
Maintain Disciplined Liquidity Reviews
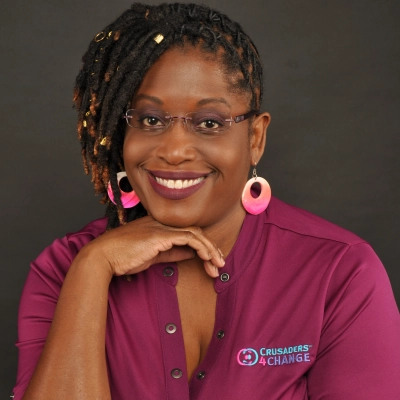
The most important thing any entrepreneur needs to master is consistent cash flow management. Ever since I became an Accredited Financial Counselor in 2008, I’ve made it a priority to track every penny of income, expenses, and debt through a spending plan. I brought that same rigor to my business, Crusaders for Change®, LLC, when I started it in 2016. By checking our cash flow at least twice a month, we’ve managed to stay rock-solid for over a decade.
This habit was a lifesaver when I joined the Goldman Sachs 10,000 Small Businesses program in 2025 (Baltimore Cohort). Digging into the nitty-gritty of our P&L statements and balance sheets could have been overwhelming, but because I already had such clear records, I was able to analyze our financial health with total confidence. That clarity gave me the push I needed to scale up and set some real growth goals.
Today, this discipline is at the core of everything we do. Whether I’m mentoring other business owners or helping clients get out of debt, improve their credit, save, and more, I lead by example. I’ve learned firsthand that a spending plan isn’t just some boring piece of paperwork. It’s the essential tool that takes you from just getting by to truly thriving.
Reinvest Early Gains For Speed
You can’t be greedy about the very first money you’re making. That’s the rule that really helped us grow and scale much faster. When we started Kontra, we had 5 people on board, now after 2 years, there is almost 50 of us. When we were launching, we’ve all sworn not to be greedy for the profits in the early days, but set a flat salary for everyone, quite low, and dedicated 100% of the extra profits to further growth.
We could have given ourselves bonuses at the end of the year, but we all knew it’s better to invest this money into building even better team and delivering even better results. In the short term, we could have taken more money to our pockets, but we focused on the long run, and re-invested almost everything we’ve managed to make.
Thanks to that, our ARR has surpassed our predictions by 46%, and we’re now making more than we ever thought we’ll be making with Kontra. Nonetheless, we still avoid being greedy, and heavily focus these funds on growing even more, to be more profitable in the future.
Price Work To Reflect Risk
One concept every entrepreneur should understand is pricing for risk, not just cost. Many businesses calculate labour and overhead accurately but ignore uncertainty, rework exposure, delays and decision changes. In technical industries, risk is part of the financial equation. If it is not priced in, the business effectively absorbs it for free.
That lesson became clear after a complex project where the scope looked straightforward at first but required far more coordination than expected. The direct costs were covered, yet the unmanaged risk eroded margin. I changed how complexity was assessed during quoting and built clearer allowances into pricing. That protected profitability and improved expectations on both sides.
Protect Optionality With Lean Spend
Cash runway is really optionality, not a scoreboard. After YC said no I could have chased validation; instead I watched which customers paid repeatedly for the same outcome, Reddit and ChatGPT visibility with proof, and doubled down there while keeping headcount tiny. That discipline let us grow ARR without raising, because I wasn’t funding experiments that didn’t show up in retention or revenue within weeks.
Track Earned Value Against Plan
We believe every entrepreneur should understand earned value even if we do not use the formal term. We do not judge performance by money spent or invoices sent. We judge it by how much real progress is achieved compared to the plan. This helps us avoid false confidence when work looks busy but falls behind outcomes.
We used this thinking while reviewing active projects that looked financially on track at the same time. Spending matched our plan but completion did not keep pace in real time. We noticed the gap early and made changes in staffing and sequencing across teams. This helped us avoid delay and reduced customer frustration across work in practice.
Turn Capex Into Shared Infrastructure
Treat your Capex as an investment and build your internal systems so well that one day they become infrastructure for the rest of the market. We wanted to tell real stories that people actually cared about. To avoid the risk of speaking into the void, we built a solution that scans social media conversations to identify the exact narrative gaps from our brand. The engine worked so well that we scaled it up and unleashed it into the world.
Most often, a business’s internal challenges are not isolated. Whatever walls you are running into, the rest of the industry is running into them, too. Infrastructure can be an idea, philosophy, software, or hardware that helps you solve difficult problems to achieve more efficiency. Whatever it is, make it reusable and shareable with the rest of the industry. Most of the time, this pays off over decades. But it creates the ultimate business growth.

Differentiate Valuation From Buyer Attractiveness
The financial concept every entrepreneur needs to understand is that your business valuation and your business attractiveness are not the same number, and confusing the two is exactly why 80 percent of businesses never sell.
A business broker or a CPA will often look at your EBITDA, apply a multiple, and give you a range of what your business could sell for. That number reflects what your financials say your business is worth. But it does not reflect what a buyer will actually pay, because buyers are not buying your P&L. They are buying what happens to the business after you leave. And if you hold all the relationships, make all the key decisions, run the sales process, and carry the institutional knowledge of how everything works, what a buyer is actually acquiring is a dependency on you. That is often times not worth the multiple the valuation expert gave you.
Up to 70 percent of what determines a business’s attractiveness is intangible. Structural capital: the systems, processes, and IP that run without you. Human capital: the depth of leadership that can make decisions without you. Customer capital: whether revenue is concentrated in relationships only you can maintain, or distributed across a base that transfers with the business. Social capital: the brand, reputation, and market position that exists independent of your personal presence. None of that shows up on the P&L. All of it determines if someone finds your business attractive or not.
Two things that feel true but are not: that working hard builds value, and that the business is worth what the valuation says it’s worth. Both are NOT automatically true.
Buyers do not care what your EBITDA multiple says. They care about predictability: can this business perform without you in it? Can they service the debt they took on to buy it, pay their investors, and see a clear return? That requires a business built around asset value, not income value.
The owners who close at the number they planned for understood what buyers actually find attractive. They knew the EBITDA set a ballpark. They also knew that the ballpark means nothing if a buyer cannot see a future in the business that does not depend on the seller showing up every day.
Valuations give owners a false sense of security. They see a number and believe the work is done. It is not. The number tells you what the math says. It does not tell you whether anyone will actually write the check for it.
Separate Business And Personal Accounts
I think the most important thing for every entrepreneur to understand and do early on is to make sure to separate business spending from personal spending. This helps to simplify tax prep, makes it easier to apply for loans, and also maintains your corporate veil, giving you the legal protection you’ll need in case of litigation. Super simple concept, but fundamental and important.
Adopt AI Where It Pays Back
I have been running CuraDebt for 24 years. Debt settlement involves immense stress, incoming leads, compliance calls, staff turnovers, consumer, tax, business, and student debts. The use of AI did not come to us through a planned process; rather, it found us at our most stressed.
The first issue was volume pressure. Too many leads, not enough time. The salespeople wasting all day on leads that did not want anything at all. Follow ups delayed lost business. Training could not always be constant because there would always be turnover.
AI came in handy in the following ways; organizing leads in an expedient manner, writing repetitive emails, extracting information from company materials without having to search for them manually. At EverLife Capital, it aided in creating concise summaries of research and notes.
It will not help bad structure. Poor sales processes will still fail, but more quickly. The questions of compliance and judgment remain where they have always been: with individuals working in debt collection. Most results depend on the quality of the input.
After having been around so long, the point is apparent. It works as repetition and speed, not control. If it cuts down back-and-forth, it pays its way. If it requires continuous monitoring, it isn’t saving time.
Assess Total Cost Of Ownership
One financial concept every entrepreneur should understand is total cost of ownership. It is easy to look at the obvious price of something, like a monthly payment, a software fee, or an upfront cost, and assume that is the full picture. But in business, the real cost often includes much more, such as time, admin work, taxes, compliance risk, employee frustration, and long-term maintenance.
We have seen this come up often with vehicle reimbursement programs. For example, a flat car allowance can look simple because the company pays the same amount each month. But once you look closer, there may be added costs from tax inefficiencies, manual tracking, inconsistent reimbursements, and employees feeling that the program is not fair. Understanding the full cost helped us look beyond what seemed easiest on the surface and focus on reimbursement approaches that were more accurate, manageable, and fair for mobile employees.